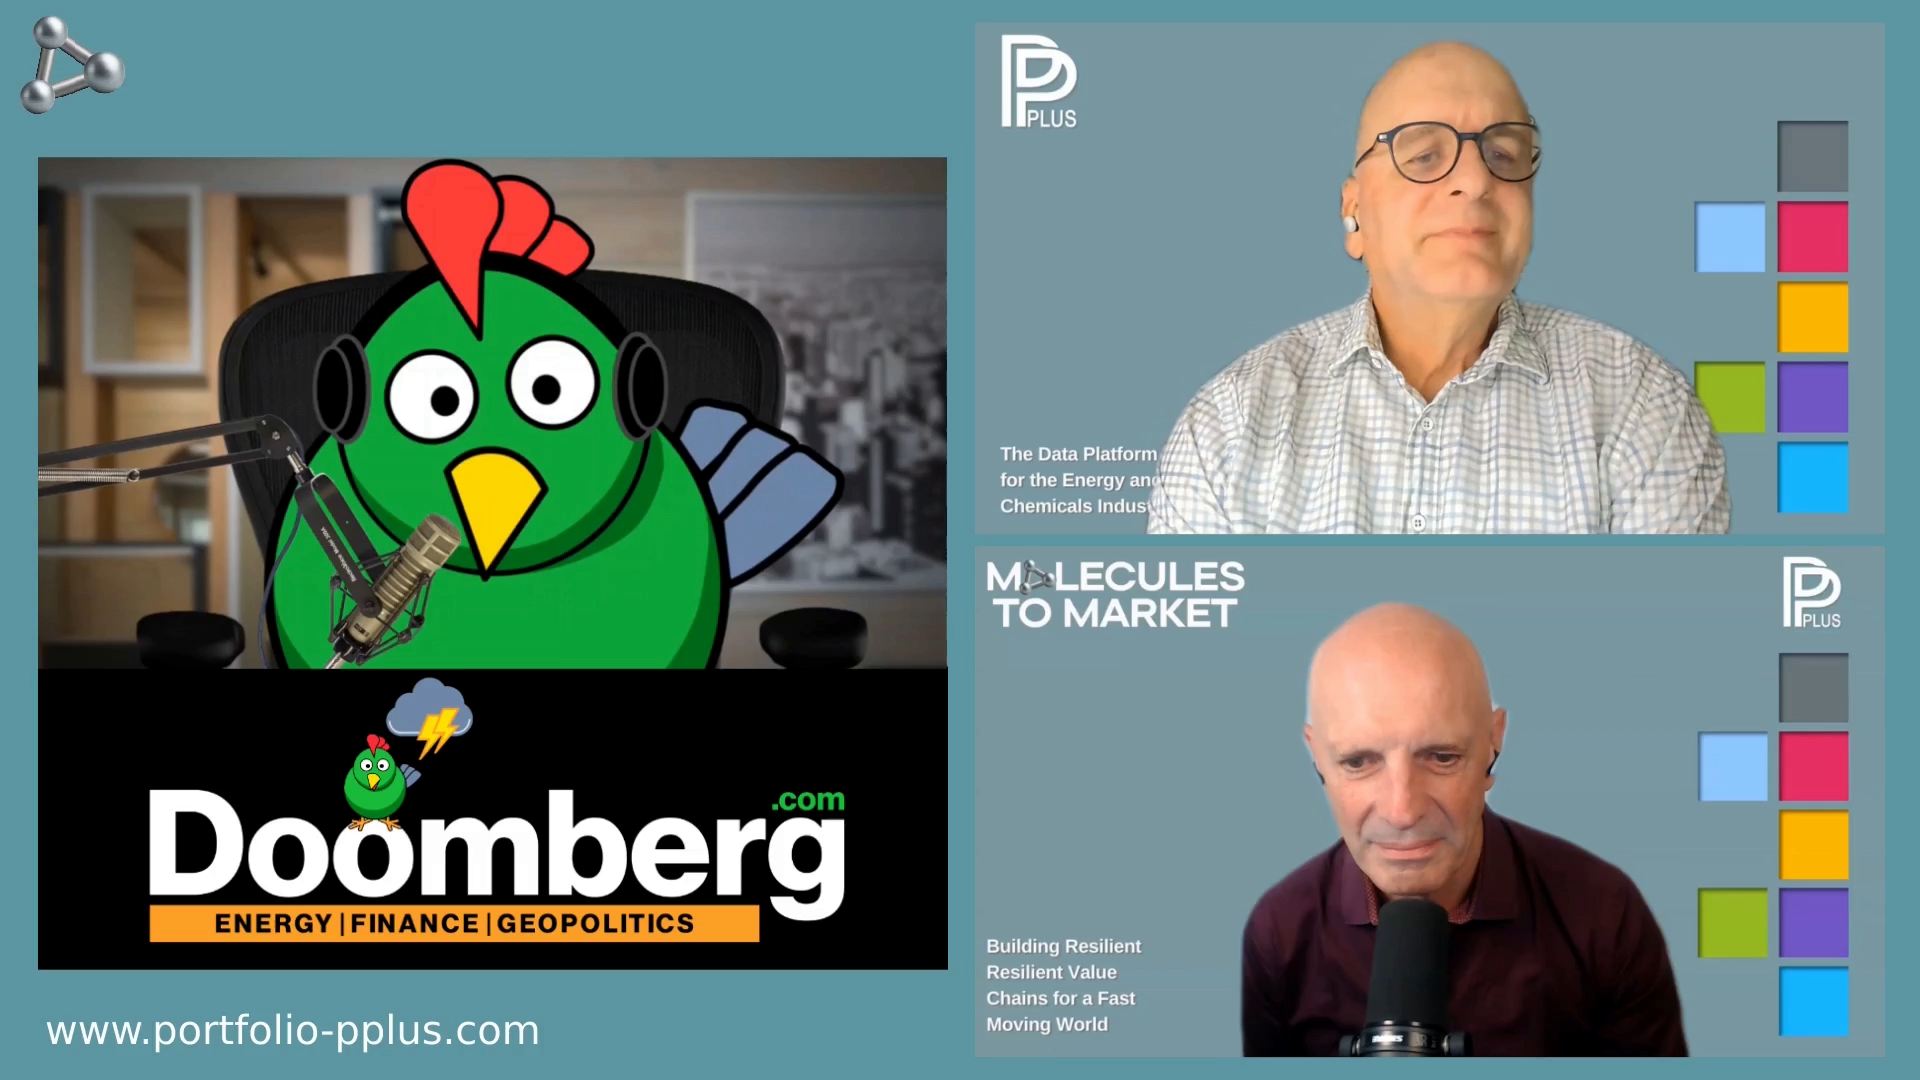
🎬 VIDEO — The Future of the Hydrocarbon Sector with The Doomberg

📋 SUMMARY
Energy security is not simply a question of how much oil or gas a region produces. It also depends on the quality of its feedstocks, the configuration of its refineries, the resilience of its supply chains—and the political choices it is willing to make. 🛢️🌍 In this wide-ranging conversation, Doomberg joins Molecules to Market to examine the growing mismatch between energy resources and the products modern economies actually need. From North America’s abundance of light hydrocarbons and NGLs to the global shortage of heavy crude, we explore why Brent at $114 tells only part of the story—and why diesel markets can reveal far more about the system’s underlying stress. The discussion moves across the Atlantic to contrast US self-sufficiency with Europe’s structural vulnerabilities: the legacy of Groningen, resistance to domestic shale development, a widening transatlantic gas-price gap, and the consequences of relying on suppliers while leaving difficult industrial decisions unresolved. Along the way, we consider refinery ownership, private equity, China’s integrated industrial model, and why there are no painless solutions—only trade-offs. ⚖️ Finally, we look beyond the immediate crisis: Africa, India and the Middle East as future centres of demand and investment; LNG’s expanding role in trucking and shipping; jet fuel and the emerging light-fuel paradigm; and what all of this means for investors evaluating simple versus complex refineries. This is a grounded discussion about molecules, infrastructure, capital and geopolitics—and why the next energy cycle may reward a very different industrial footprint from the last. ⚡
✨ HIGHLIGHTS
• The NGL Abundance Paradox: Why North America’s extraordinary supply of light hydrocarbons does not automatically translate into self-sufficiency in every fuel and feedstock. 🧪
• Heavy Crude & the Diesel Squeeze: What constrained heavy-oil flows, refinery configuration and product demand reveal behind the headline Brent price. 🛢️
• Two Atlantic Realities: US resource strength and Western Hemisphere integration versus Europe’s exposure to imported energy and limited domestic buffers. 🌎
• Europe’s Uncomfortable Choices: Groningen, shale, energy-intensive industry and the political consequences of leaving difficult options unexamined. 🇪🇺
• The Gas-Price Divide: The strategic implications of European gas prices around $30 versus approximately $2.50 in the United States—and what that means for industrial competitiveness. 📉
• Ownership & Industrial Resilience: How private equity, short investment horizons and fragmented accountability can affect strategic refining assets. 🏭
• Lessons from China: Why robust refining depends on finance, governmental support, scale and integration.
🔗 • No Solutions, Only Trade-offs: A candid framework for balancing affordability, security, emissions, reliability and political feasibility.
⚖️ • The Light-Fuel Shift: LNG-powered trucks and ships, evolving jet-fuel demand, and the implications for tomorrow’s refinery product slate. 🚛
• Investment Guidance: How to think about simple versus complex refineries, regional demand growth, Middle Eastern scenarios after Hormuz, and North America’s “Project Turtle.” 💡
⏱️ CHAPTERS
-
00:00:00: Welcome to Molecules to Market (ppPLUS) — intro & guest welcome
-
00:02:56: Doomberg: who we are — energy, finance & geopolitics since 2021
-
00:04:54: Feedstocks: the abundance of NGLs & “Trend Lightly”
-
00:10:15: Energy arbitrage & what to do with the heavies
-
00:16:18: Brent at $114: heavy crude in short supply & the diesel crisis through the lens of flows
-
00:24:07: Regional outlook: US self-sufficiency & the Western Hemisphere (Uwe)
-
00:29:00: Europe’s dilemma — Groningen, shale & the politics of not looking
-
00:33:49: Gas price gap: Europe $30 vs US $2.50
-
00:40:02: Europe: “not at the table, part of the menu”
-
00:48:11: Degrading ownership: private equity & the German refinery debate
-
00:50:45: What makes a robust refining industry — the China model
-
00:51:53: The path out: there are no solutions, only trade-offs
-
00:57:10: Looking outward: Africa, India & the Middle East
-
00:59:45: “Praying for rain” — cycles, honeymoon periods & forgetting
-
01:01:28: The light-fuel paradigm shift: LNG trucks, shipping & jet fuel
-
01:07:24: Guidance for investors: simple vs complex refineries
-
01:10:48: The Middle East: Qatar–Cheniere & scenarios after Hormuz
-
01:15:40: Project Turtle — North America looks inward
-
01:17:31 Wrap-up & what’s next: Asia and Africa
🔍 RESOURCES
👤 Doomberg — Energy, Finance & Geopolitics
🛢️ ppPLUS Refining Module
🏭 ppPLUS Encyclopedia of Technologies
📩 Suggest a guest or topic: media@portfolio-pplus.com
🎙️ Molecules to Market is a program by Portfolio Planning PLUS (ppPLUS), bringing together technology, economics, and real facility-level data to give industry professionals a grounded, technical view of the global energy and petrochemical landscape — beyond the headlines.
energyarbitrage #oilprice #dieselcrisis #ngl #naturalgasliquids #feedstockprices #doomberg #energyprices